How to Finance an Outdoor Kitchen in Rhode Island
Rhode Island homeowners typically finance an outdoor kitchen through a home equity loan, a HELOC, a personal loan, or a contractor financing plan. The right option depends on how much equity you have, your credit profile, and whether your project will be built in one phase or several stages.
An outdoor kitchen is one of the larger investments a Rhode Island homeowner can make in their backyard, and the cost often runs well beyond what most people expect to pay out of pocket. Once you've settled on a layout and a rough budget, the next question is usually how to pay for it.
For a detailed breakdown of what these projects typically cost across the state, our guide on outdoor kitchen cost in Rhode Island is a useful starting point before you look at financing.
This guide walks through the main financing routes available to Rhode Island homeowners, what each option involves, and what to consider before signing on with a lender or contractor financing plan.
Understanding What You're Financing
Before comparing lenders, it helps to have a clear picture of total project cost. Outdoor kitchen pricing in Rhode Island depends on the size of the layout, the materials selected, and how many built-in appliances are included.
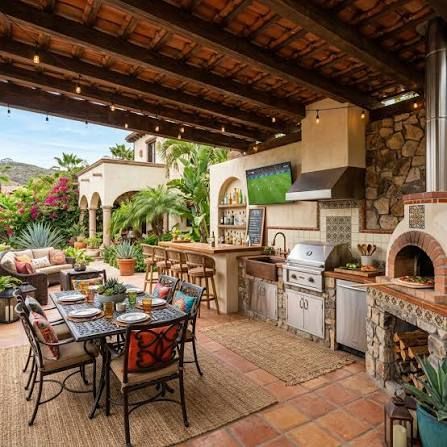
A basic setup with a grill and storage sits at the lower end of the market, while a full custom build with a pizza oven, bar seating, and premium finishes sits well above it.
Labour rates, permit fees, and site preparation also affect the final number, and these can vary by municipality. Getting a written quote from a licensed contractor before applying for financing gives you an accurate figure to work from, rather than borrowing based on a rough estimate.
Home Equity Loans
For homeowners who have owned their property for several years, a home equity loan is often the most practical way to finance a larger outdoor kitchen build. This type of loan gives you a lump sum at a fixed interest rate, repaid over a set term, usually somewhere between five and twenty years.
Because the loan is secured against your home, interest rates tend to be lower than unsecured financing options. This makes a home equity loan well suited to projects where the full scope and cost are already known.
A few points worth considering with a home equity loan:
- Fixed monthly repayments make budgeting straightforward
- Interest may be tax-deductible when funds are used for home improvement, though this should be confirmed with a tax adviser
- Rates are generally lower than personal loans or credit cards
- Loan amounts can comfortably cover mid-range to high-end projects
Local credit unions and community banks across Rhode Island often offer competitive terms on home equity products, and it's worth comparing a few before committing.
Home Equity Lines of Credit (HELOCs)
A HELOC works differently to a home equity loan. Rather than receiving a single lump sum, you're given access to a revolving line of credit that you draw from as needed. This structure suits homeowners who plan to build their outdoor kitchen in stages, or who aren't yet certain of the final cost.
During the draw period, which is usually five to ten years, you typically only pay interest on the amount you've actually borrowed. Once that period ends, you move into the repayment phase.
This flexibility can work well if you want to start with a core setup, such as a built-in grill and bench space, and add features like a refrigerator or pergola later. You're only carrying interest on what you've used, which keeps costs down during construction.
The same logic applies if your outdoor kitchen is part of a broader patio project. Our guide to Rhode Island patio financing options covers how HELOCs and other products apply to combined hardscaping and kitchen builds.
Personal Loans
Not every homeowner has enough equity to draw on, particularly those who've purchased more recently. In that case, an unsecured personal loan is a reasonable alternative.
Personal loans don't require your home as collateral, which means no appraisal and generally a faster approval process. The trade-off is a higher interest rate compared with home equity products. For smaller to mid-sized outdoor kitchen projects, a personal loan can still be a practical choice.
When comparing personal loan options, it's worth checking for:
- A competitive interest rate relative to your credit profile
- No prepayment penalties
- A repayment term that matches your budget, typically two to seven years
- A lender that reports repayment history to the major credit bureaus
Rates and terms vary between lenders, so getting a few quotes before committing is a sensible step.
Contractor Financing
Many outdoor kitchen contractors in Rhode Island offer their own financing arrangements, either directly or through a third-party lending partner. This can be convenient, since approval is often handled as part of the quoting process rather than through a separate application.
Some of these plans include promotional terms, such as a set period with no interest charged, provided the balance is cleared within that window. It's important to read the terms carefully. Deferred interest promotions can apply a large retroactive interest charge if the balance isn't paid off before the promotional period ends.
If you're working with a contractor in a town like Central Falls or elsewhere in northern Rhode Island, it's worth asking directly whether financing is available and what the repayment terms actually look like.
Homeowners in that area researching hardscaping and outdoor kitchen builders can see examples of local project scope through our Central Falls paver patio and hardscaping page.
Cash-Out Refinancing
A cash-out refinance involves replacing your existing mortgage with a larger one and taking the difference in cash. This option can make sense if current mortgage rates work in your favour, or if you were already planning to refinance for another reason.
It does extend the life of your mortgage and comes with closing costs, so it's generally better suited to larger renovation projects rather than a standalone outdoor kitchen build. Homeowners considering this route should speak with a mortgage lender about how it affects their overall loan term before proceeding.
Using a Credit Card for Smaller Expenses
A credit card is rarely the most cost-effective way to finance a full outdoor kitchen, but it can play a supporting role. If you're covering smaller costs, such as appliances or lighting, a card with a 0% introductory APR period can spread payments over a few months without accruing interest, provided the balance is cleared before the promotional rate ends.
This approach carries more risk than other financing methods, since standard interest rates on credit cards are typically much higher once the introductory period expires. It works best as a supplement to another financing method rather than the primary way to fund the project.
Tips for Getting Approved and Securing a Reasonable Rate
A few practical steps can help when applying for any of the financing options above:
- Check your credit score before applying. Most lenders look for a score of 680 or higher for home equity products, with stronger scores typically securing better rates.
- Work out your loan-to-value ratio. Most home equity lenders will lend up to 80 to 85 percent of your home's appraised value, minus what's still owed on your mortgage.
- Ask whether a HELOC lender allows you to lock in a fixed rate on part of the balance.
- Compare offers from a few lenders, including local credit unions, rather than accepting the first quote.
Is an Outdoor Kitchen a Good Investment in Rhode Island?
An outdoor kitchen generally holds its value well in Rhode Island's property market. Outdoor living space is a feature many buyers look for, and a well-built kitchen adds usable square footage to a backyard.
Beyond resale considerations, there's the everyday benefit. Rhode Island summers are relatively short, and an outdoor kitchen extends the months a backyard actually gets used.
Final Thoughts
Working out how to finance an outdoor kitchen in Rhode Island comes down to matching the right product to your situation. A home equity loan or HELOC tends to suit larger builds where equity is available, while a personal loan or contractor financing plan may fit better for smaller projects or homeowners who'd rather not use their property as collateral.
Getting a detailed, written quote before applying for any financing option will make it much easier to choose a plan that fits your budget and your long-term plans for the property.
Outdoor Kitchen Financing Calculator
Estimate your monthly payments and compare financing approaches before planning your Rhode Island outdoor kitchen project.
Your Financing Estimate
Estimated amount to finance
Estimated monthly payment
Repayment Summary
Estimated total repayments:
Estimated total interest:
Planning Notes
Estimates are based on the figures entered and assume a fixed interest rate with regular monthly payments. They exclude lender fees, closing costs, taxes, insurance, and other charges. HELOC draw-period figures assume no additional borrowing and an unchanged balance. Actual rates, eligibility, payment schedules, and terms depend on the lender and financing agreement.
Frequently Asked Questions
What is the best way to finance an outdoor kitchen in Rhode Island?
There's no single best option for every homeowner. A home equity loan or HELOC generally suits larger, well-defined projects, while a personal loan or contractor financing plan can work better for smaller builds or homeowners without significant home equity.
How much does an outdoor kitchen typically cost in Rhode Island?
Costs vary depending on size, materials, and appliances. Our
outdoor kitchen cost guide breaks down pricing by project tier and by location across the state.
Can I use a HELOC to build an outdoor kitchen in stages?
Yes. A HELOC allows you to draw funds as needed, which suits projects built over time, such as starting with a basic grill setup and adding features like a refrigerator or pergola later.
Is contractor financing a good option for an outdoor kitchen?
It can be convenient, particularly for promotional no-interest periods, but it's important to confirm the repayment terms and what happens if the balance isn't paid off within the promotional window.
Does financing a patio work the same way as financing an outdoor kitchen?
The same general financing products apply to both. Our guide on
Rhode Island patio financing options explains how these choices apply when a patio and outdoor kitchen are being built as part of the same project.