Rhode Island Patio Financing Options Explained
Adding a patio is one of the most popular home improvement projects among Rhode Island homeowners, but figuring out how to pay for it can feel more complicated than picking out pavers.
Rhode Island patio financing options vary widely, from home equity products to personal loans and manufacturer financing, and the right choice depends on your credit profile, how much equity you have in your home, and how soon you want the work completed.
This guide walks through the main financing routes available to Rhode Island homeowners so you can make an informed decision before signing a contract.
Why Financing a Patio Makes Sense for Many Homeowners
A new patio adds genuine value to a Rhode Island property, whether you're in Providence, Warwick, Cranston, or a coastal town like Narragansett. Outdoor living space has become a priority for many buyers, and a well-built patio can make a home more enjoyable to live in right away, not just when it eventually sells.
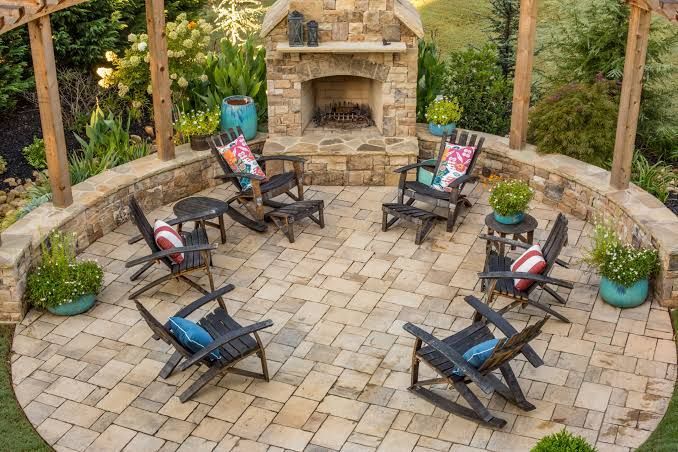
That said, patio costs in Rhode Island can run anywhere from a few thousand dollars for a basic concrete slab to well over $10,000 for natural stone or paver installations with added features like fire pits, seating walls, or lighting.
Paying the full amount upfront isn't realistic for every household, which is why financing has become a common part of the planning process rather than an afterthought.
Home Equity Loans and HELOCs
For homeowners who have built up equity, a home equity loan or home equity line of credit (HELOC) is often the most cost-effective way to finance a patio project.
A home equity loan gives you a lump sum upfront with a fixed interest rate and a set repayment schedule. This option works well if you already know the total project cost and want predictable monthly payments.
A HELOC, on the other hand, works more like a credit card secured against your home. You draw funds as needed during the construction period, and interest is only charged on what you actually use. This flexibility can be useful if your patio project includes phases, such as building the hardscaping first and adding an outdoor kitchen later.
Both options typically offer lower interest rates than personal loans or credit cards because they're secured by your property. The trade-off is that your home serves as collateral, so it's worth speaking with a financial adviser or lender about what level of borrowing makes sense for your situation.
Personal Loans for Patio Projects
If you don't have enough equity built up, or you'd rather not use your home as collateral, an unsecured personal loan is another route. These loans are based primarily on your credit score and income rather than your home's value.
Personal loans generally come with higher interest rates than home equity products, but the application process is often quicker and doesn't require an appraisal. For smaller projects, such as a basic concrete or paver patio under $10,000, a personal loan can be a reasonable middle ground between speed and cost.
It's worth comparing rates from a few lenders, including local Rhode Island credit unions, since rates and terms can differ noticeably between institutions.
Contractor and Manufacturer Financing
Many patio contractors in Rhode Island partner with third-party lenders to offer financing directly at the point of sale. This can be convenient because you're approved as part of the quoting process, without needing to apply separately through a bank.
These financing plans often include promotional terms, such as a set period with no interest, provided the balance is paid off within that window. It's important to read the fine print carefully, as some plans apply deferred interest retroactively if the balance isn't cleared in time. Ask your contractor directly about the repayment terms, any fees, and what happens if payments are late.
If you're considering a larger outdoor renovation that includes features beyond the patio itself, such as an outdoor kitchen, it's worth looking at how financing structures differ for combined projects, since lenders may treat them differently depending on total project scope.
Cash Out Refinancing
For homeowners planning a larger-scale outdoor renovation, a cash-out refinance is another option worth considering. This involves refinancing your existing mortgage for more than you currently owe and taking the difference in cash.
This approach can make sense if current mortgage rates are favourable compared to your existing loan, or if you're already planning to refinance for other reasons. However, it does extend the life of your mortgage and involves closing costs, so it's generally better suited to larger projects rather than a standalone patio installation.
Homeowners weighing a cash-out refinance against other financing routes should also factor in how the project compares to other home improvements. For context on typical costs for larger-scale work, our guide to home addition costs in Rhode Island breaks down pricing considerations that apply to bigger renovation decisions.
Credit Cards: When It Might Make Sense
Using a credit card to pay for a patio is generally not the most cost-effective option due to higher interest rates, but it can work for smaller projects if you have a card with a 0% introductory APR period. This allows you to spread payments over several months without accruing interest, provided you pay off the balance before the promotional period ends.
This approach carries more risk than other financing methods, since interest rates typically jump significantly once the introductory period expires. It's best reserved for modest projects or as a supplement to another financing method rather than the primary funding source for a full patio installation.
Questions to Ask Before Choosing a Financing Option
Before committing to any financing method, it helps to ask a few practical questions:
- What is the total cost of the project, including materials, labour, and any permits required by your local Rhode Island municipality?
- What is the interest rate, and is it fixed or variable?
- Are there any fees, such as origination fees or early repayment penalties?
- How long is the repayment term, and what will the monthly payment actually be?
- Does the financing option require your home as collateral?
Getting clear answers to these questions upfront can prevent surprises later and help you compare financing options on an equal footing.
Working with a Local Rhode Island Contractor
Choosing a contractor familiar with Rhode Island's climate, permitting requirements, and soil conditions matters just as much as choosing the right financing plan. Local contractors are often better positioned to provide accurate cost estimates, which in turn makes it easier to select the right financing option for your budget.
If you're located in the Warwick area and exploring patio options, it's worth reviewing the work of local paver patio builders in Warwick, RI to get a sense of typical project scope and design options available in your area before finalising your financing plan.
Making the Right Choice for Your Budget
There isn't a single best financing option for every Rhode Island homeowner. A home equity loan or HELOC tends to suit larger projects where you have equity to draw on, while a personal loan or contractor financing plan may be more appropriate for smaller installations or homeowners who prefer not to use their property as collateral.
Whatever direction you choose, take the time to get a detailed, written quote from your contractor before applying for financing. Knowing the full project cost upfront, including any site preparation or drainage work specific to Rhode Island's soil and climate, will help you select the Rhode Island patio financing option that actually fits your budget and your long-term plans for the property.
Rhode Island Patio Financing Calculator
Find out how different financing options could fit your patio project. Enter your project amount, contribution, interest rate and repayment period to compare estimated monthly payments, total repayment and interest.
The starting APRs and repayment periods below are illustrative examples, not current lender offers. Edit them to match the terms you are considering.
Financing Comparison Summary
Adjust the assumptions above to compare the estimated repayment amounts across financing methods.
This calculator is for educational planning only and is not a loan offer or financial advice. Initial APR and term values are hypothetical and should be replaced with actual lender terms. Results assume a fixed APR and equal monthly payments that fully repay the financed amount. They do not include lender fees, closing costs, tax effects, rate changes, promotional deferred interest or credit-card minimum-payment rules. A HELOC may have variable rates and a separate draw period. A cash-out refinance replaces an existing mortgage, so this calculator does not calculate the effect on your full mortgage balance or remaining loan term. Confirm eligibility, collateral requirements, repayment conditions and all applicable fees directly with a lender.